
What earnings reports reveal about a company’s performance matters to investors who want facts, not noise. Earnings reports condense quarterly results into three core statements and a management narrative that together show sales momentum, profitability, cash generation, and near-term risks. This guide gives practical reading steps and highlights the metrics most likely to predict future value, so a reader can move from headline reaction to measured judgment.
Key Takeaways
- Earnings reports reveal a company’s sales momentum, profitability, cash generation, and risks through income statements, balance sheets, cash flow statements, and management discussions.
- Investors should analyze revenue growth, EPS trends, operating cash flow, margins, and leverage ratios to assess a company’s financial health and future value.
- Consistent operating cash flow exceeding net income indicates high-quality earnings that reflect real cash generation.
- Management guidance should be compared to analyst expectations and past forecasts to gauge reliability and detect optimism or conservatism.
- A systematic reading sequence—from revenue and EPS versus consensus, through cash flow and balance sheet checks, to management discussion—helps transform headline numbers into informed judgments.
- Careful scrutiny and comparison to peers and market context allow investors to distinguish meaningful performance signals from quarterly noise.
What Earnings Reports Include And How To Read Them
Fact first: an earnings report is primarily four parts, the income statement, balance sheet, cash flow statement, and management discussion, and each answers a distinct question about the business.
The income statement answers: did sales and profit rise or fall this period? It lists revenue, costs, operating income, and net income plus EPS (earnings per share). Investors should scan for one-time items (asset sales, legal settlements) and recurring operating results. A single quarter can show volatility: year-over-year and sequential comparisons reveal trend direction.
The balance sheet answers: what does the company own and owe today? It shows cash, inventory, receivables, long-term debt, and shareholders’ equity. Liquidity ratios like current ratio or quick ratio tell whether the firm can cover short-term obligations. A rapidly rising debt balance or shrinking cash cushion is a red flag.
The cash flow statement answers: is profit backed by cash? This statement separates cash from operations, investing, and financing. Strong operating cash flow confirms that reported earnings translate into real cash. Negative free cash flow for several quarters may be fine for high-growth companies with heavy investment, but it demands explanation.
The management discussion (MD&A) answers: what does leadership expect next? Executives explain drivers, risks, and guidance here. Investors should compare guidance to analyst expectations and previous guidance for evidence of conservatism or optimism. For readers wanting a broader business-news context, note how earnings tie into market trends on RipRoar’s coverage of market updates.
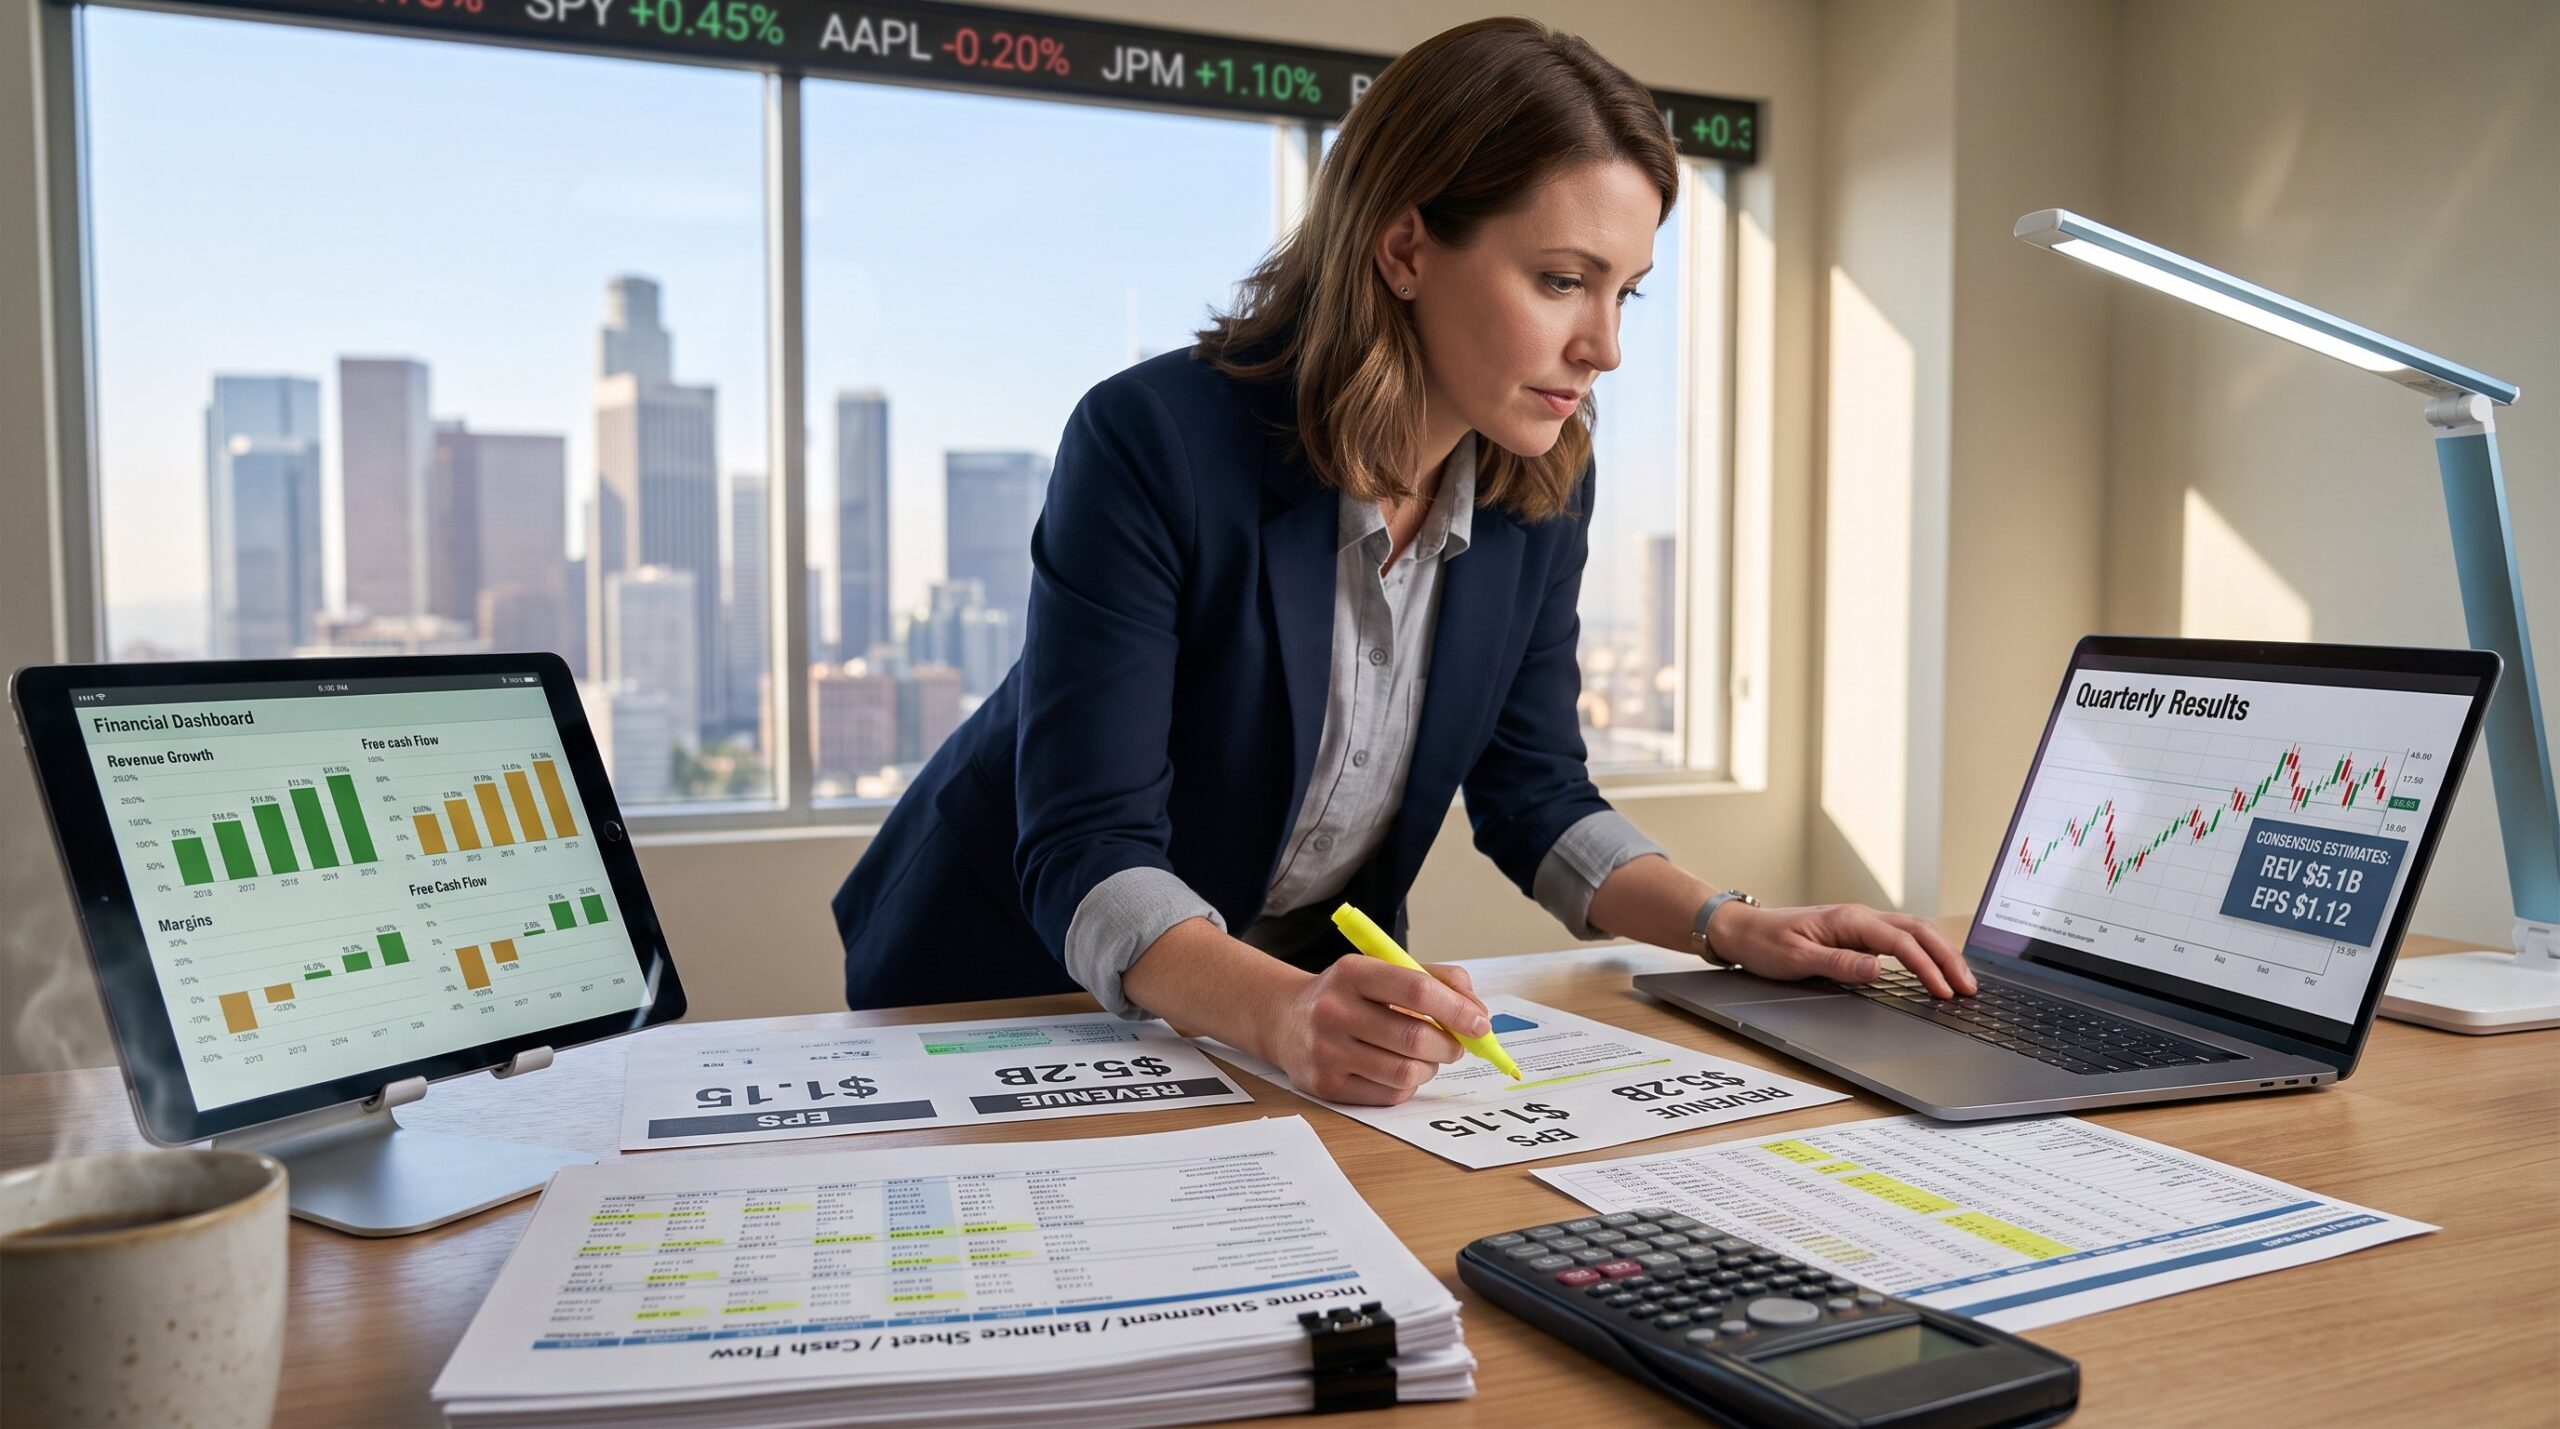
Reading steps: 1) start with revenue and EPS versus consensus: 2) check cash flow from operations: 3) scan balance sheet for liquidity or debt changes: 4) read the management discussion for guidance shifts. That sequence moves an investor from headline numbers to the deeper evidence behind them.
Key Metrics That Reveal Growth, Profitability, And Financial Health
Fact first: a short list of metrics, revenue growth, EPS, margins, operating cash flow, and leverage ratios, separates noise from signal.
Revenue shows demand. A company that posts 12% year-over-year revenue growth signals expanding sales: 2% growth signals stagnation. Investors should always compare revenue growth to the company’s addressable market and to peers. Rapid top-line gains that aren’t accompanied by improving margins or cash flow can hide unsustainable spending.
EPS compresses profit per share but can be distorted. Share buybacks raise EPS without improving operating profit. One-time gains or tax adjustments can also swing EPS. Compare adjusted EPS (which removes one-offs) to GAAP EPS and read footnotes to reconcile differences.
Margins measure efficiency. Gross margin shows product profitability, operating margin shows core business efficiency, and net margin shows bottom-line conversion. A business that expands gross margin from 28% to 34% over two years likely gained pricing power or lowered unit costs, a tangible competitive advantage.
Cash flow matters more than accounting profit. Operating cash flow that exceeds net income consistently is a sign earnings are high quality. Free cash flow, operating cash flow minus capital expenditures, is the cash available for dividends, buybacks, or debt reduction. A software firm that generates $450 million in free cash flow can fund growth without external borrowing.
Leverage and liquidity close the loop. Debt-to-equity and current ratio reveal financial flexibility. A company with $3.2 billion in cash and a debt-to-equity of 0.2 has more runway than one with $120 million in cash and a debt-to-equity of 2.0.
Practical warning: don’t take guidance at face value. Management has incentives to manage expectations. Contrast guidance with historical forecasting accuracy and peer outlooks. For investors who need help cutting through jargon, RipRoar’s primer on reading business news explains how to spot spin and focus on verifiable facts.
Conclusion
Earnings reports condense a company’s recent reality into numbers and a narrative. Investors should prioritize revenue trends, EPS context, guidance consistency, margin behavior, cash generation, and balance-sheet resilience. Read results with skepticism, compare to peers, and use primary filings and trusted summaries to verify claims. That disciplined approach turns quarterly noise into actionable insight.