
How Interest Rate Changes Affect Businesses and Consumers is a practical question for anyone running a company or a household in 2026. Interest rates set the price of borrowing and the reward for saving: when central banks move policy rates, markets and balance sheets shift quickly. This guide gives clear, actionable explanations of why rates change, how firms and people feel the effects, and which sectors win or lose, so readers can make better financial and operational decisions.
Key Takeaways
- Interest rate changes directly impact borrowing costs and savings returns, influencing both businesses and consumers immediately.
- Businesses face higher interest expenses, leading many to delay investments, reduce output, or raise prices cautiously due to competitive pressures.
- Consumers experience increased loan payments and often reduce big-ticket purchases when rates rise, while savers benefit from higher returns on deposits.
- Sector impacts vary: banks and insurers typically gain from higher rates, whereas real estate, retail, and growth-oriented tech firms often suffer reduced demand and valuation declines.
- Effective preparation includes running stress tests for interest rate increases, prioritizing liquidity, reducing variable-rate debt, and carefully managing capital projects.
- Timely adjustments to financing strategies, such as locking in fixed rates and building emergency savings, help both firms and households navigate rate fluctuations with lower risk.
What Interest Rates Are And Why They Change
Fact: Interest rates are the price of borrowing and the return on saving. Central banks set short-term policy rates and use them to fight inflation or support growth. When inflation runs above target, policymakers raise rates to cool demand: when growth slows, they cut rates to stimulate borrowing.
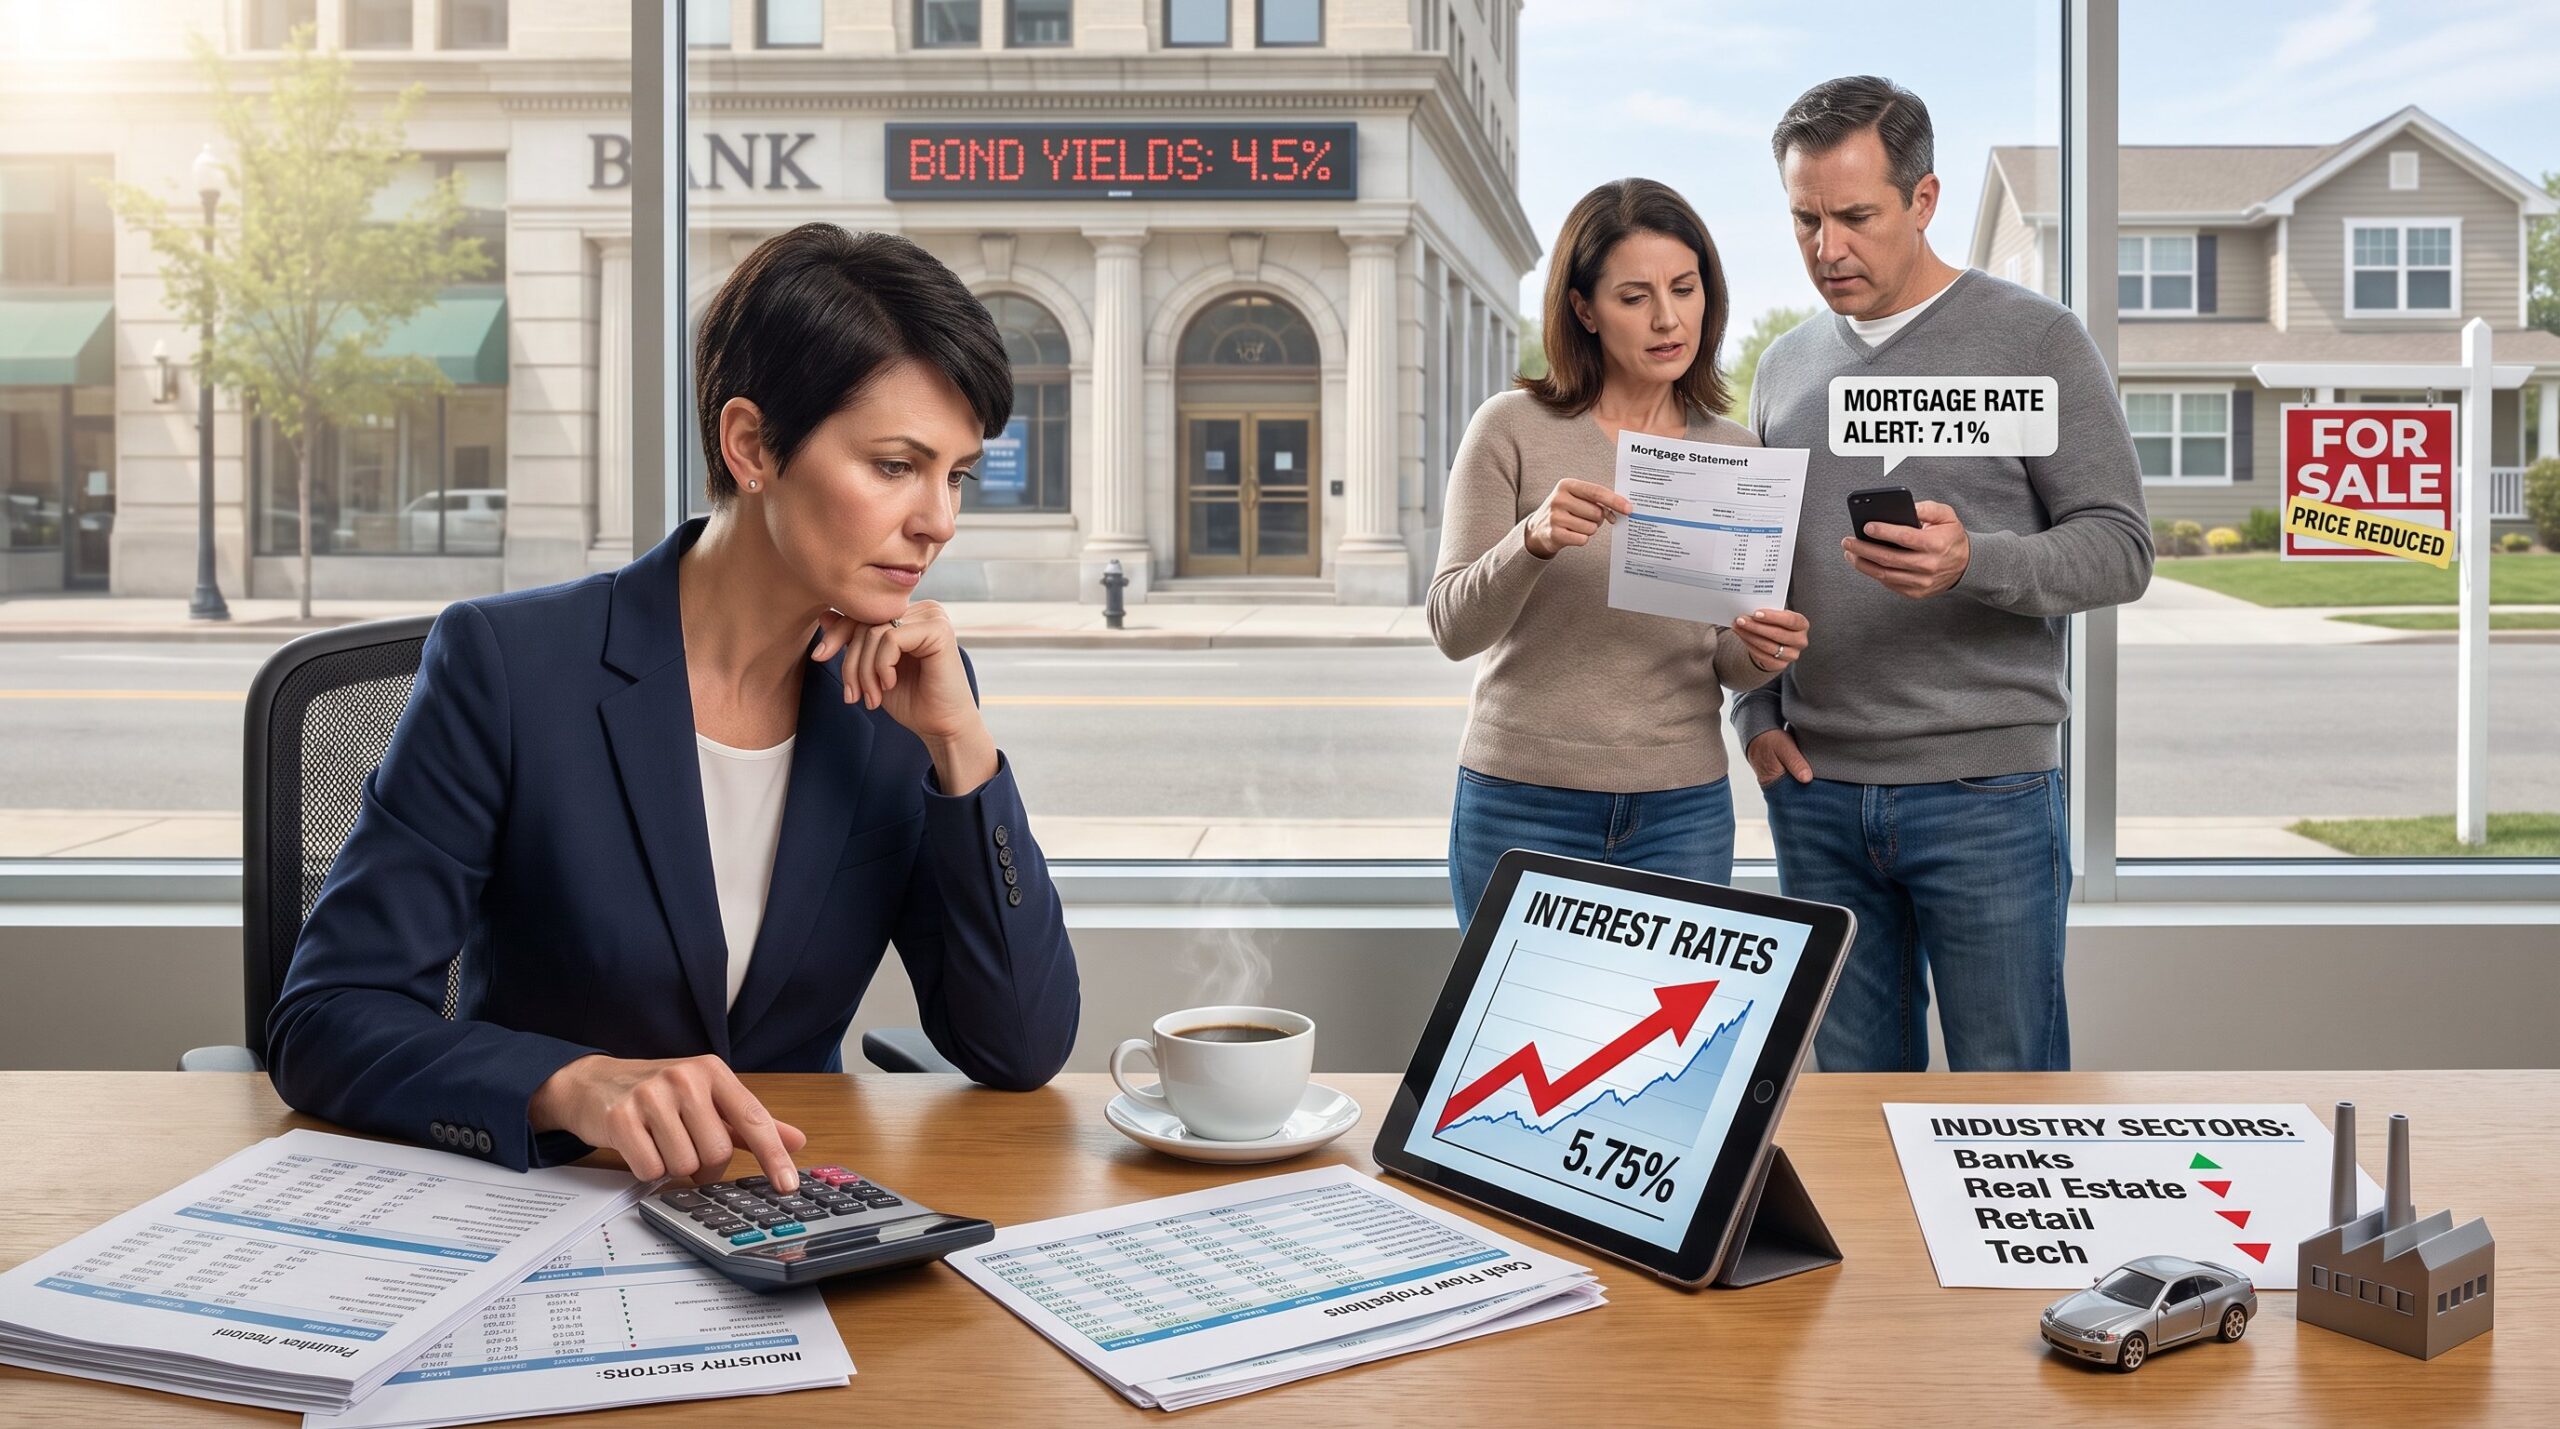
Context and mechanics: A central bank decision changes the policy rate, which then influences bank lending rates, bond yields, and deposit returns. Markets translate policy moves into mortgage and corporate loan rates within days or weeks. For example, in 2026 many markets tightened after high inflation readings, and the transmission raised mortgage and corporate costs. That channel explains why companies see higher interest expenses and why consumers face pricier loans almost immediately.
Concrete detail: A 1 percentage-point rise in a bank’s reference rate can increase a variable mortgage payment by hundreds of dollars a month for a typical borrower with a $300,000 loan. Firms with floating-rate debt may see annual interest expense rise by 10–25% depending on leverage. These precise changes matter for cash flow planning and short-term budgets.
How Rate Changes Impact Businesses: Costs, Investment And Pricing
Fact: Higher rates raise borrowing costs and reduce investment. Businesses pay more to service loans and issue bonds, which directly squeezes operating cash.
Investment decisions: As the cost of capital rises, many firms delay or cancel capital projects. Surveys show capital spending plans shrink when rates climb: small manufacturers often defer machinery purchases first. For a $2 million expansion financed at floating rates, a 1 point rise can add roughly $20,000 per year in interest, enough to change the payback calculation.
Pricing and margins: Some firms pass higher costs to customers by raising prices, but competitive pressure limits this option in many markets. If demand is price-sensitive, companies cut output or trim margins instead. Retailers with thin margins may accept lower profits for a season rather than lose market share.
Operational and financial tradeoffs: Firms prioritize liquidity, keeping more cash, reducing inventory turns, and slowing hiring. Highly leveraged firms suffer most: refinancing becomes costlier and covenant pressure rises. Growth-oriented companies with long-duration cash flows see equity valuations fall as discount rates increase.
Operational and Financial Effects On Businesses
Fact: Cash flow is often the first channel of stress. Rising rates convert revenue into debt service faster than firms can adjust costs.
Details: A business that previously spent $100,000 annually on interest might pay $125,000 after a rate shift, $25,000 less available for wages, maintenance, or R&D. That tradeoff forces difficult choices: cut staff, delay product launches, or renegotiate supplier terms. Companies that misjudge timing face liquidity crunches: one mid‑sized firm in 2025 discovered its cash buffer covered only two months of higher payments and had to seek emergency credit.
Practical metrics: CFOs should track interest coverage ratios, rolling maturities, and stress-test a 200–400 basis point increase. Those three numbers give a clear sense of refinancing risk and operational vulnerability.
How Rate Changes Affect Consumers: Borrowing, Saving And Spending
Fact: Consumers pay more when rates rise and earn more when rates fall. The net effect usually reduces household spending when borrowing costs increase.
Borrowing effects: Mortgage, auto, and personal loan rates move with policy and market rates. A 0.75 percentage-point increase in mortgage rates can push monthly payments up by several hundred dollars on common loan sizes, cutting disposable income. Credit card rates rise faster and hit lower-income households hardest because those balances typically carry the highest rates.
Saving response: Higher interest makes saving more attractive: deposit rates rise, so savers earn more on cash balances. But most households hold more debt than interest-bearing assets, so net cash flow often tightens even though better rates on savings.
Spending and behavioral change: Households delay big purchases, homes, cars, major renovations, when financing costs climb. They also prioritize paying down high-rate debt, which reduces discretionary spending. In contrast, when rates fall, consumers tend to refinance and increase spending on durables.
Housing, Credit Cards, And Big-Ticket Purchases For Consumers
Fact: Housing and high-rate consumer credit respond fastest to rate moves. Mortgage rate jumps slow transactions and weigh on prices.
Concrete examples: After a 2026 rate rise, buyer demand for single-family homes fell in many regional markets: listings stayed longer and some sellers cut prices by 2–4% to regain traction. Credit card holders facing variable APRs saw monthly minimums rise, pushing some households to reduce dining out, subscriptions, and nonessential purchases. For big-ticket goods, a typical new-car loan financed over 60 months becomes noticeably more expensive with higher rates, shifting purchases toward used cars or delaying upgrades.
Sector-Specific Winners And Losers (Banks, Real Estate, Retail, Tech)
Fact: Rate changes create clear sector winners and losers: banks often gain: rate‑sensitive sectors lose.
Winners: Banks and insurers typically benefit from higher rates because net interest margins widen and bond yields improve returns on reserves. Asset managers with large cash holdings earn better short-term returns. For related guidance, consult the site guide.
Losers: Real estate, REITs, utilities, and long-duration tech firms tend to underperform. Higher mortgage and refinancing costs depress property demand and push REIT yields higher to compete with safer bonds. Utilities with heavy debt loads feel immediate margin pressure, while high-growth tech names face valuation compression as discount rates rise.
Evidence and context: Central bank moves in 2026 had asymmetric effects: lenders quoted stronger earnings outlooks, while some REITs reported rising cap‑rates and lower transaction volumes. Media coverage of those shifts included coverage of the ECB’s rate moves in 2026, which illustrate how regional policy alters mortgage costs and consumer spending patterns, and a Reuters market outlook summarized those global drivers.
Sector-by-sector specifics:
- Banks: Benefit via higher lending spreads. They still face credit risk if recession follows tight policy.
- Real estate/REITs: Face higher cap rates and fewer buyers: property transactions slow.
- Retail/consumer discretionary: Sales dip as credit costs and cash flow constraints bite.
- Technology and growth stocks: Valuations fall as future earnings are discounted more heavily.
Practical signal: Investors should watch rate-sensitive metrics, mortgage applications, loan delinquencies, and bank net interest margins, to spot turning points.
How Businesses And Consumers Can Prepare And Respond
Fact: Preparation reduces risk. Both firms and households should run scenarios for higher rates and weaker demand.
Business actions: Firms can reduce leverage, lock in fixed-rate financing, extend debt maturities, and build cash buffers. They should reprioritize capital projects and run sensitivity analysis on projects that assume low discount rates. Companies tracking news and market data will also benefit from curated updates: for ongoing industry signals, the site’s coverage of market trends and company updates provides context and cadence for decision-making when rates shift via a centralized resource.
Consumer actions: Households should minimize variable-rate debt, time refinancing when fixed rates are attractive, and grow emergency savings to cover 3–6 months of expenses. Those with adjustable mortgages should calculate the payment impact of a 200 basis point increase and plan a budget buffer accordingly.
Honest warnings and tradeoffs: Locking into fixed rates gives certainty but can carry higher initial costs. Cutting investment preserves cash but may forgo growth opportunities. One manufacturing owner relented that after prematurely cancelling a $400,000 equipment purchase during a 2022‑2023 rate rise, the firm lost market share when demand returned, an important lesson on balance.
Tactical checklist (short):
- Stress-test cash flow for +200–400 bps moves
- Reprice or hedge rate exposure where feasible
- Build 3–6 month liquidity
- Prioritize high-return projects
Closing insight: Preparing now avoids reactive decisions later: small, specific steps, like fixing a single large loan, can change a company’s or household’s risk profile significantly.

