
How to Read Business News Without Getting Lost in the Jargon is a practical skill anyone can learn. The first step is to stop treating headlines like puzzles and treat them like short reports: identify the actor, the number, and the consequence. This short guide shows clear steps, exact definitions, and a repeatable workflow that helps readers parse earnings, mergers, macro updates, and regulatory reports without confusion. It uses plain examples, real pitfalls, and daily tools to make business news readable and useful.
Key Takeaways
- Reading business news effectively requires decoding jargon by focusing on core elements like the actor, key numbers, and consequences in each headline.
- Understanding fundamental financial terms—revenue, profit, margins, and EPS—is essential for interpreting the true meaning behind business reports.
- Business news falls into distinct categories—earnings, macroeconomics, M&A, and regulation—each requiring a tailored reading approach to grasp relevant impacts.
- A five-step workflow—identify actor, event type, numbers, context, and judgment—helps readers extract meaningful insights from any business article.
- Using daily tools like glossaries, earnings primers, and concise newsletters enhances understanding and reduces time spent deciphering complex reports.
- Always verify figures with primary sources such as press releases or investor presentations to avoid being misled by unsupported claims in business news.
Why Business Jargon Makes News Hard To Follow
Fact first: business jargon turns concrete events into opaque sentences, so readers lose the story behind the numbers. Journalists combine shorthand, accounting terms, and market shorthand (like “beat,” “miss,” or “guidance”) that assume prior knowledge.
Why that matters: a headline such as “Company X beats EPS” hides three decisions, how revenue was counted, which costs were included, and whether one-off gains changed the result. Many readers read “beats” as purely positive, but a 5% EPS beat can coexist with falling revenue and rising debt.
Concrete example: a June earnings story might report revenue of $1.2 billion and “adjusted” profit of $150 million. “Adjusted” removes items management calls non-recurring. That matters because one-time gains can inflate profit today and make future expectations inaccurate.
Common traps readers face:
- Everyday words have technical meanings: “profit” often means net income after tax, not cash in the bank.
- Percentages mask scale: a 10% margin on $10 million revenue is not the same as 10% on $10 billion.
- Guidance and quarter-over-quarter comparisons hide seasonality.
Practical warning: when headlines use jargon without numbers, readers should pause. Numbers, definitions, and historical context tell the real story.
Build A Simple Foundation: Key Terms And Concepts
Start with a single line: revenue → costs → profit → EPS. That sequence explains how a company moves money from sales into shareholder value.
Revenue is total sales before subtracting costs. Profit (net income) is what remains after all costs, taxes, and interest. Margins measure profit as a share of revenue: they show efficiency. EPS, earnings per share, splits net income across outstanding shares and tells investors how much income each share captures.
Why this foundation stops confusion: once a reader locates revenue and net income, they can check margins and EPS to see whether growth is healthy or fragile. For example, revenue up 8% with margins down 200 basis points signals rising costs.
Common, precise definitions readers should memorize:
- Revenue: total sales or top-line receipts.
- Gross margin: (revenue − cost of goods sold) / revenue.
- Operating margin: operating income / revenue.
- Net margin: net income / revenue.
- EPS: net income divided by diluted shares.
Practical tip: when a report lists “adjusted” figures, look for a reconciliation table. That table shows which costs were removed and whether those items are likely to recur.
Financial Metrics Made Simple (Revenue, Profit, Margins, EPS)
Answer first: revenue is top-line sales: EPS is profit per share.
Revenue gives scale: profit and margins give quality. If revenue grows 12% but net margin falls from 15% to 8%, growth could be masking inefficiency. EPS helps compare companies with different share counts: a rising EPS usually signals improving per-share returns, but share buybacks can boost EPS without real profit growth.
Concrete numbers help: a retailer with $500 million revenue and a 5% net margin earns $25 million net income. If outstanding shares equal 10 million, EPS equals $2.50.
Small study habit: always note the base period (year-over-year vs. quarter-over-quarter) and whether the report cites GAAP or adjusted figures. Adjusted metrics can be valid, but reconciliation is essential.
Market Structure And News Types (Earnings, Macro, M&A, Regulation)
Answer first: business news fits into a few clear buckets, earnings, macro, mergers & acquisitions (M&A), and regulation, and each demands a different reading lens.
Earnings: look for revenue, margins, EPS, and guidance. Earnings move stock prices because they change expectations.
Macro: economic releases (inflation, unemployment, GDP) affect entire sectors. A 0.5 percentage-point rise in inflation can alter interest-rate expectations and change valuation multiples.
M&A: ask who pays, who benefits, and what the purchase price implies. A $2 billion acquisition funded by stock can dilute EPS: funded by cash can reduce net cash reserves.
Regulation: rule changes often change costs or address future liabilities. A new safety standard can add short-term costs but prevent fines later.
Practical warning: readers should mark the news type before diving into metrics. That framing makes it easier to spot which numbers matter.
Step-By-Step Reading Workflow For Any Business Article
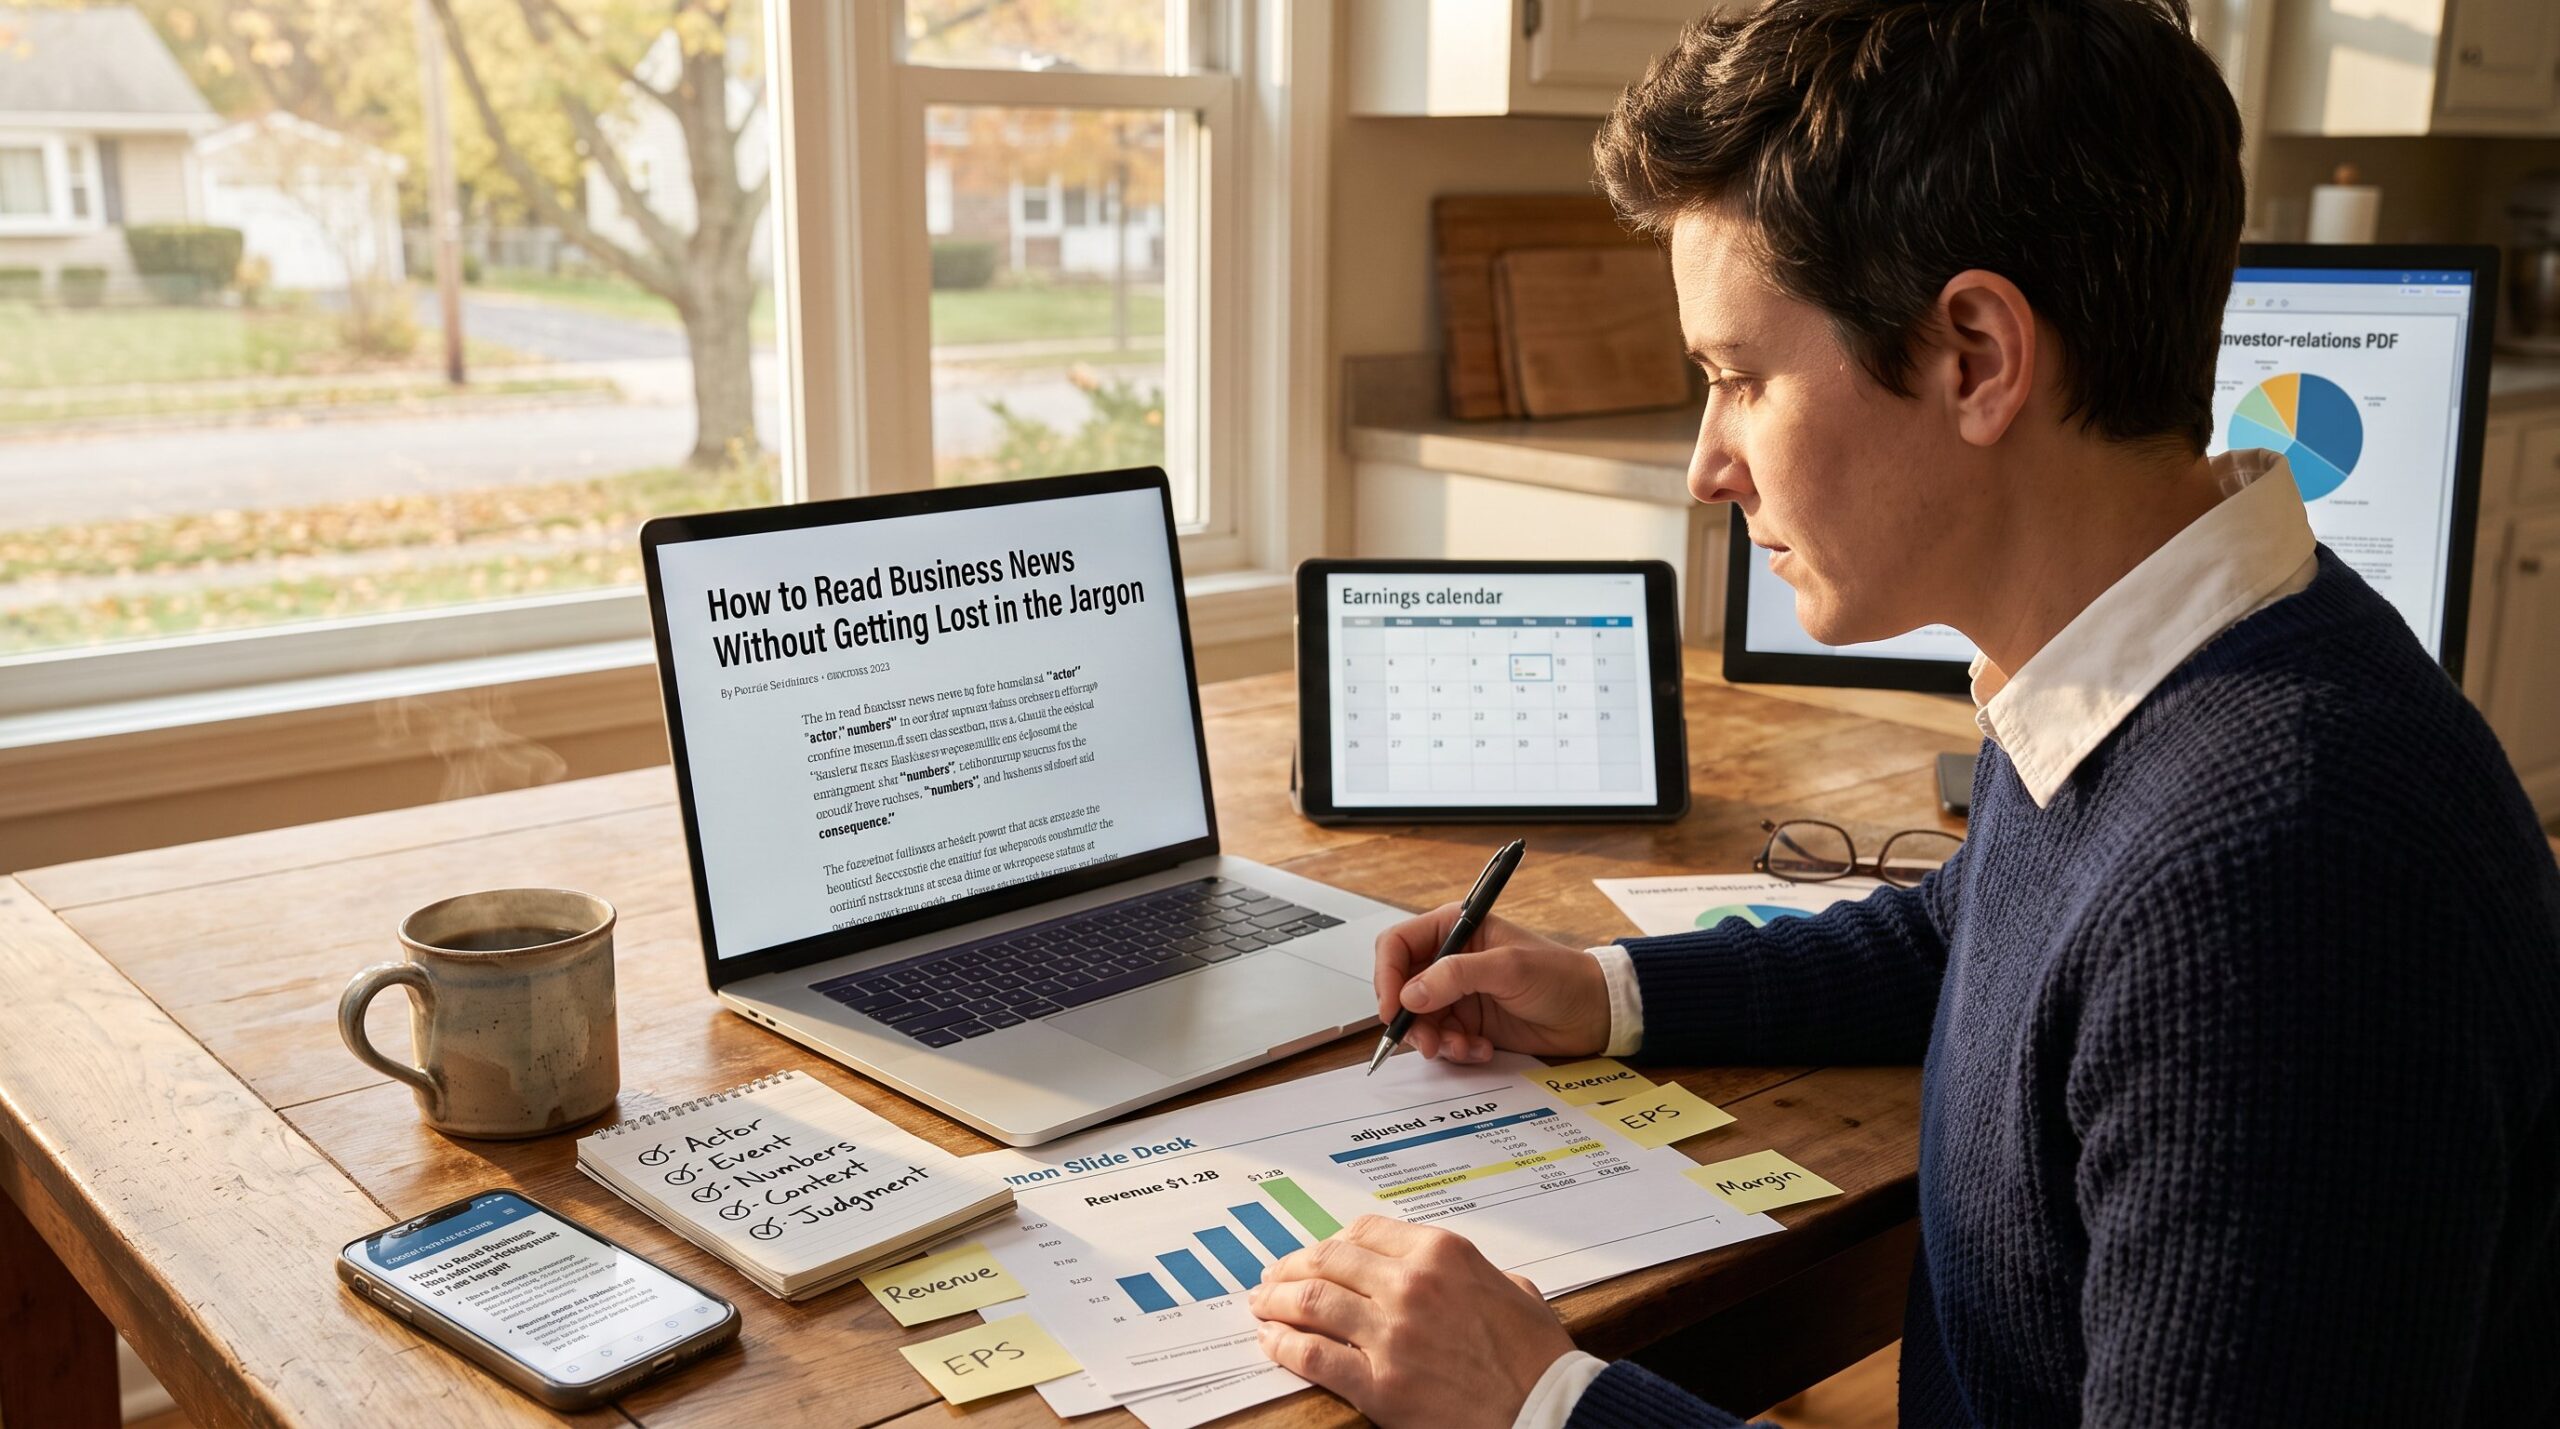
Answer first: follow a five-step workflow, actor, event, numbers, context, and judgement.
- Actor: identify the company, government agency, or market named. Who is acting?
- Event: label the story type, earnings, M&A, macro, or regulation.
- Numbers: pull the key figures (revenue, profit, margin, EPS, price paid, percentage changes). Write them down.
- Context: compare to prior periods and guidance. Is growth organic or from one-offs?
- Judgement: ask what changes going forward, costs, demand, or capital needs?
Concrete example: reading an earnings release for a software firm.
- Actor: SoftwareCo.
- Event: quarterly earnings.
- Numbers: revenue $320M (+18% YoY), net income $24M, non-GAAP EPS $0.40, churn down 0.8 points.
- Context: analysts expected $310M revenue: last quarter had $300M. Guidance raised for next quarter.
- Judgement: revenue growth plus lower churn suggests sustainable expansion: raised guidance implies management confidence.
Use this workflow to separate signal from noise. If an article quotes only opinions without numbers, jump to the company release or an earnings slide deck for the facts. For basics and broader coverage, the site publishes a central guide to business coverage: readers can use the site’s overview as a starting point and then test articles against the five-step workflow with the business coverage guide.
Practical warning: many articles highlight a single quote from a CEO. Quotes matter for tone, not math. Always pair a quote with the numbers it references.
Tools, Sources, And Habits To Stay Clear And Confident
Answer first: use three daily tools, a glossary, an earnings primer, and a short trusted newsletter. These reduce friction and cut lookup time to under five minutes.
Habit 1, Quick glossary checks: keep a bookmark to a concise finance glossary that explains gross margin, operating margin, net margin, and diluted EPS. That prevents misreading headline language.
Habit 2, Earnings primers: before an earnings call, scan a one-page primer with last quarter’s numbers, consensus estimates, and key questions. That primes a reader to spot surprising deviations.
Habit 3, a short newsletter: subscribe to a plain-language newsletter that summarizes the market in 3–5 bullets each morning. A daily habit turns unfamiliar terms into routine context.
Concrete tools to use daily:
- A browser bookmark with a business glossary.
- Company investor-relations pages for primary figures.
- An earnings calendar to track report dates.
Quick Reference Tools, Glossaries, And Newsletters To Use Daily
Answer first: practical, fast references save time and reduce error.
Recommended quick checks: a one-page earnings checklist, a two-column glossary (term → single-sentence definition), and a five-bullet daily summary email. When reading, consult an investor-relations slide deck for reconciliations and a one-page press release for headline numbers.
Useful internal links: when distinguishing company-level reports from sector trends, readers can compare coverage with a short primer on company vs industry. For interpreting acquisition impact on employees and customers, the site’s piece on mergers and acquisitions is a concise companion. To decode profit and per-share figures in reports, a quick read of the earnings reports primer helps translate reconciliations into plain language.
Practical warning: avoid sources that provide headlines without backing numbers. Primary documents (press releases, investor decks, regulatory filings) verify claims. If an article cites a figure without source, treat it cautiously.
Behavioral tip: after a month of using these tools, most readers cut time-to-understand from 30 minutes to about ten minutes per article. That time savings converts directly into better judgement when reacting to market news.

